

How to Calculate the Break-Even Point on a Refinance
Use this mortgage refinance guide to calculate break even, estimate closing costs and see how long you need to stay to benefit from refinancing.
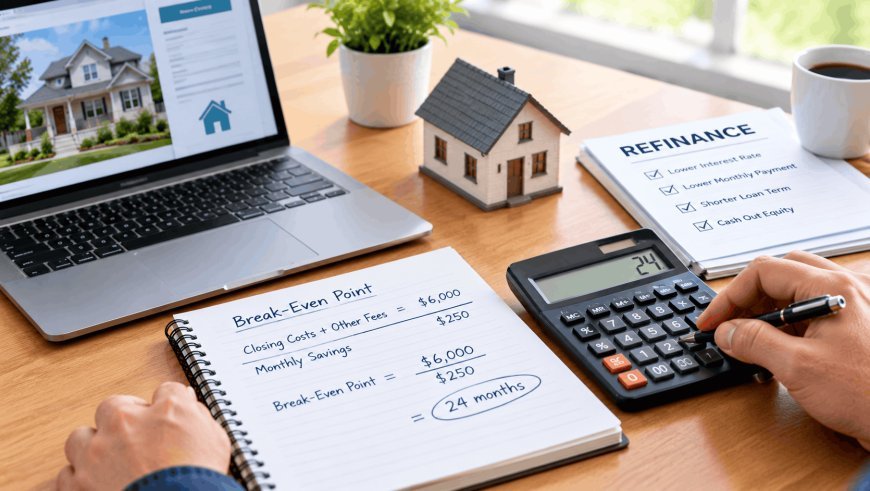
Divide your total closing costs by the amount you save each month. The result is how many months it takes to earn back what you spent. If you'll stay in the home longer than that, a mortgage refinance usually pays off. If you won't, it probably doesn't.
Mortgage Loan Refinance Break-Even: The Short Answer
1. The One-Line Formula
Break-even months equal total closing costs divided by monthly savings. That's it. If your costs are $9,000 and you save $250 a month, you break even in 36 months. Every month after that, the savings are yours to keep.
2. Why It Matters More Than the Rate
A low rate looks great in an ad. But a mortgage refinance isn't free, and the rate only tells half the story. Think of it like buying a more efficient furnace. The lower gas bill is real, but you have to live in the house long enough for the savings to cover what you paid for the furnace. Break-even tells you how long that takes.
What Goes Into Your Closing Costs
1. Costs That Count
Add up every fee you pay to get the new loan. Closing costs commonly run from about 2% to 5% of the loan amount, though it varies by lender, location, and loan size.
Common Fee Categories
-
Lender origination or underwriting fees
-
Appraisal
-
Title search and title insurance
-
Escrow or settlement fees
-
Recording fees
-
Credit report fees
-
Discount points, if you buy them
2. Costs That Do Not Count
Some items on your closing statement aren't true costs of refinancing. Prepaid property taxes, homeowners insurance, and the money that funds your escrow account are yours either way. You'd pay them eventually, so leave them out of your break-even number. Mixing them in makes the refinance look worse than it is.
3. Rolling Costs Into the Loan
Many borrowers add closing costs to the new loan balance instead of paying cash. That can help your cash flow, but it raises your loan amount, and you pay interest on those costs for years. Keep that in mind when you run the numbers.
How to Find Your Real Monthly Savings
1. Compare Principal and Interest Only
Take your current principal and interest payment and subtract the new one. Use the exact numbers from your loan estimate, not a rough guess.
2. Leave Taxes and Insurance Out
Taxes and insurance don't change because you refinanced, so strip them out of both sides. If your lender's quote shows a full payment with escrow, back it out first so you're comparing apples to apples.
3. Watch the Loan Term
If you're moving from a loan with 22 years left into a brand new 30-year loan, your payment might drop for a simple reason: you stretched it out. That's lower payment, not necessarily lower cost. Compare the same term when you can, or look at total interest too.
A Worked Example on a $400,000 Balance
These numbers are illustrations, not quotes. Real rates and costs vary.
1. The Numbers
Say you owe $400,000. Your current loan is a 30-year fixed at 7%, with a principal and interest payment of about $2,661 a month. A lender offers you a 30-year fixed at 6%, and your new payment would be about $2,398. Closing costs come to 3% of the loan, or $12,000.
2. The Math
Monthly savings: $2,661 minus $2,398 equals about $263. Break-even: $12,000 divided by $263 equals about 46 months, or just under four years.
3. Reading the Result
So, will you still live in this home in four years? If yes, this mortgage loan refinance pays for itself, and after month 46 you pocket roughly $263 a month. If you might sell in two years, you'd lose money. A "yes" or "no" to that one question often settles the whole decision.
What Changes if You Roll the Costs In
Say you add the $12,000 to the loan instead of paying cash. Your new balance is $412,000, and your payment at 6% comes to about $2,470. Your monthly savings drop to about $191, and you owe $12,000 more. You haven't escaped the cost. You've financed it. Compare total interest over the time you plan to keep the loan, not just the monthly payment.
Break-Even for Points, Shorter Terms, and Cash-Out
1. Discount Points
Points are fees you pay up front to lower your rate. The same formula applies. Say one point costs $4,000 and trims your payment by $60 a month. Divide $4,000 by $60 and you get about 67 months. If you plan to hold the loan for ten years, that's a good deal. If you'll move in four, skip it.
2. Shorter Terms
Going from a 30-year to a 15-year loan usually raises your monthly payment, so there are no monthly savings to divide by. Here, break-even works differently. Compare the total interest you'd pay on your current loan over its remaining life with the total interest on the new one, then subtract your closing costs. If the interest savings beat the costs, it's a win.
3. Cash-Out Loans
A cash-out mortgage refinance replaces your loan with a bigger one, so a simple monthly-savings formula doesn't capture the full picture. Compare the cost of the cash against other ways to borrow. A home equity line of credit leaves your first mortgage alone, which matters if you have a low rate. The Taylor Weiner Team offers a digital HELOC with an application that takes about five minutes, and approved applicants can see funding in as few as five days.
Mistakes That Throw Off Your Math
1. Ignoring How Long You Will Stay
Break-even only helps if you're honest about your timeline. Job changes, growing families, and market shifts all affect how long people stay. If there's a real chance you'll move before your break-even date, be cautious.
2. Resetting the Clock
Ten years into a 30-year loan, a new 30-year loan adds ten years of payments. Your monthly bill might fall, but total interest could climb. One fix: ask for a term that matches your remaining years, or keep paying your old amount on the new loan.
3. Looking Only at the Rate
A slightly lower rate with heavy fees can lose to a slightly higher rate with light fees. Every mortgage loan refinance quote should be judged on rate, fees, and monthly payment together.
How to Get Accurate Numbers
1. Get Loan Estimates on the Same Day
Rates change daily. Ask for quotes from at least three lenders on the same day so you can compare them fairly. Credit scoring models generally treat multiple mortgage inquiries in a short window as one, so shopping won't wreck your score.
2. Ask for a Written Fee Breakdown
Request the loan estimate and read the fee sections closely. Look for points, origination charges, and third-party fees. If a lender says "no closing costs," ask where the cost went. Often it's in a higher rate or a larger loan balance.
3. Test Your Numbers in a Calculator
Plug your balance, rate, term, and costs into a calculator and try a few scenarios. Our mortgage calculators make it easy to see how a quote changes your payment. Taylor Weiner has 20 years of mortgage experience, a 5.0 rating on Google, and 450+ five-star reviews overall, and reading what past clients say about a lender's transparency is worth a few minutes before you commit.
Conclusion
1. Your Next Step
To find your break-even point, divide your true closing costs by your monthly savings, then compare that number of months with how long you plan to stay. A faster break-even means a safer bet. Watch for traps like term resets, rolled-in costs, and points that take years to pay off. When the math works, a mortgage loan refinance can put real money back in your pocket. To run your own numbers with a real person, call the Taylor Weiner Team in Seal Beach at (714) 658-4912 or apply online.
FAQs
1. What is a good break-even period?
Shorter is safer. Many borrowers look for a break-even well under the time they expect to stay in the home.
2. Do closing costs include prepaid taxes and insurance?
Those are on your closing statement, but they're not true refinance costs, so leave them out of your break-even math.
3. Is a no-closing-cost refinance really free?
Usually not. The cost is often built into a higher rate or added to your loan balance.
4. How do I calculate break-even if my payment goes up?
Compare total interest over the time you'll keep the loan, then subtract your closing costs.
5. Can I refinance more than once?
Yes, but each time you pay closing costs again, so run the break-even math every time.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0