What to Do When You Need Money Before Your Next Salary
Need money before payday? Explore practical ways to manage urgent expenses, compare borrowing options, avoid risky loan apps, and plan your next salary.
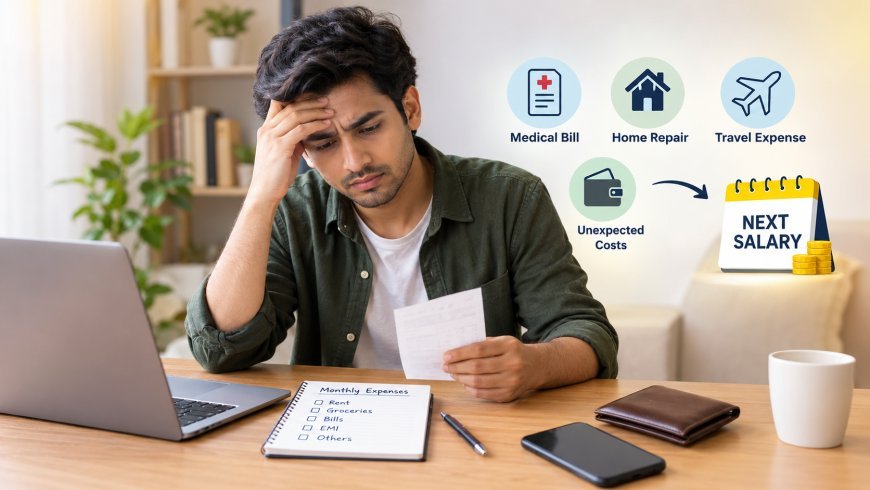
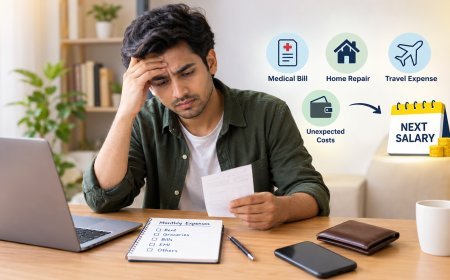
Running short of money before your next salary can be stressful. An unexpected medical bill, urgent home repair, travel expense, or delayed payment can disturb your monthly budget. Even people who manage their finances carefully may sometimes face a cash shortage.
When this happens, the first step is to understand how much money you actually need and how quickly you must arrange it. Taking the right steps can help you handle the emergency without creating a bigger financial problem next month.
1. Calculate How Much Money You Need
Before borrowing money, calculate the exact amount required to cover your immediate expenses. Separate urgent payments from those that can wait until your salary arrives.
For example, if you have ₹3,000 available but need ₹5,000 for an urgent bill, your actual shortage is ₹2,000. You may not need to borrow the entire amount.
Check your bank balance, upcoming automatic payments, and any cash you can safely use without affecting essential expenses. A clear figure makes it easier to choose an affordable solution.
2. Prioritise Essential Expenses
Not every expense needs to be paid immediately. When money is limited, focus on necessities such as food, medicines, rent, electricity, and essential travel.
You can postpone non-essential shopping, entertainment, subscriptions, and other discretionary spending until your next salary arrives.
If a bill cannot be paid on time, contact the service provider or lender before the due date. Ask whether an extension or a suitable payment arrangement is available. Communicating early may help you avoid unnecessary penalties or additional stress.
3. Check Whether You Can Use Your Savings
If you have an emergency fund, this is one situation where it may be useful. Using your own savings can help you avoid interest charges and loan processing fees.
However, do not withdraw money from an investment without understanding the consequences. Some investments have withdrawal restrictions, exit loads, or tax implications.
If you do not have an emergency fund, check whether you have money in a separate savings account or an upcoming payment that you can reasonably rely on. Avoid counting uncertain income as available cash.
4. Ask for a Salary Advance or Early Payment
If your employer allows salary advances, consider asking for a small amount against your upcoming salary. Some companies offer this facility for genuine emergencies.
Before accepting an advance, confirm how much will be deducted from your next salary and whether any fees apply.
Remember that an advance is not additional income. It reduces the money you will receive later. Make sure you can still cover rent, groceries, travel, loan EMIs, and other essential expenses after the deduction.
5. Consider Help From Family or Trusted Friends
If the shortage is small, borrowing from a trusted family member or friend may be less expensive than taking a formal loan.
Be clear about the amount, the reason for borrowing, and when you expect to repay it. Agreeing on a realistic repayment date can prevent misunderstandings.
Avoid promising repayment before you have checked your next salary and existing financial commitments. A smaller amount that you can repay comfortably is better than borrowing more than necessary.
6. Compare Short-Term Loan Options Carefully
Sometimes, savings and other sources may not be enough to cover an urgent expense. In that case, a short-term loan may be an option, provided the repayment is affordable.
Some digital lenders offer short repayment periods for people who need money quickly. If you are exploring this route, you can review this guide to 15-day loan apps in India to understand the types of options available and what to consider before applying.
Do not choose a loan based only on the advertised interest rate or the promise of quick approval. Check the following details before accepting an offer:
-
Total repayment amount: Know how much you must repay, including interest and applicable charges.
-
Repayment date: Confirm that the due date matches your expected cash flow.
-
Processing fees: Check whether fees and applicable taxes increase the actual cost.
-
Late payment charges: Understand the consequences of missing the repayment deadline.
-
Lender details: Verify the regulated lender's identity and the terms of the loan agreement.
In India, check whether the lender is a regulated bank or NBFC, or whether the digital lending app is acting on behalf of a regulated lender. Do not share your banking passwords, PINs, or OTPs with anyone claiming to arrange a loan.
7. Avoid Borrowing More Than You Can Repay
A loan may solve an immediate cash shortage, but it can create another problem if the repayment amount is too high.
Before borrowing, calculate your expected take-home salary and subtract rent, household expenses, EMIs, utilities, and other essential payments. The remaining amount shows how much flexibility you have.
For example, if you expect to receive ₹15,000 and your essential expenses and existing EMIs total ₹11,000, you have ₹4,000 left before accounting for any other upcoming costs. Taking a loan that requires a large repayment from this amount could leave you short again.
If repayment depends on taking another loan, the proposed borrowing may not be affordable. In that situation, consider negotiating the bill, reducing the amount needed, or finding another source of support.
8. Be Careful With Unverified Loan Apps
Financial emergencies can make people vulnerable to misleading advertisements and fraudulent lending offers.
Avoid apps or agents that guarantee approval without reasonable checks, demand unexplained upfront payments, or pressure you into accepting a loan immediately.
Read the privacy policy and permissions carefully. Be cautious if an app requests access to contacts, call logs, or other personal information that is not necessary for the stated service.
Keep a copy of the loan agreement and repayment schedule. If a lender's conduct appears suspicious, preserve the relevant messages and payment records and use the appropriate official grievance or complaint channel.
9. Make a Plan for Your Next Salary
Once the immediate emergency is handled, prepare a simple budget for your next salary. This can help prevent the same problem from repeating.
Start by listing your fixed expenses, including rent, EMIs, utilities, and essential household costs. Then estimate variable expenses such as groceries, transport, and medical needs.
Set aside money for upcoming bills before spending on optional purchases. If possible, begin building an emergency fund with a small amount every month.
Even saving ₹500 or ₹1,000 regularly can help you gradually build a financial cushion. The initial goal is to save enough to cover one small unexpected expense, then increase the amount over time.
If you frequently run out of money before payday, review your spending over the previous two or three months. Look for recurring expenses that can be reduced and check whether your current income is sufficient for your essential commitme
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0