



5 Costly Accounting Mistakes Property Accounting Software Can Help Avoid
Managing rental property finances requires accuracy, consistency, and careful attention to every transaction. Real estate companies regularly handle tenant payments, maintenance expenses, security deposits, supplier invoices, and financial responsibilities involving multiple property owners. Even minor bookkeeping errors can create financial discrepancies, delay reporting, and affect relationships with landlords and investors. As property portfolios expand, relying on spreadsheets and disconnected accounting records increases the risk of overlooking important financial details.
A Property Accounting Software helps businesses reduce these risks by organizing transactions, connecting financial records with individual properties, and improving accounting oversight. Understanding the most common mistakes can help landlords, property managers, and real estate companies establish stronger financial processes before small errors become expensive problems.
Why Accounting Mistakes Can Be Expensive for Property Businesses
Unlike many other businesses, real estate companies must maintain financial information across individual buildings, rental units, tenants, and owners. A single transaction may affect several records, including a tenant ledger, property income account, landlord balance, and bank reconciliation.
When these relationships are not maintained correctly, accountants may spend considerable time investigating discrepancies. Incorrect information can also affect rental collection decisions, financial statements, and owner distributions.
Specialized real estate accounting software provides a structured approach to maintaining these financial relationships, helping businesses identify inconsistencies and reduce unnecessary administrative work.
Here are five accounting mistakes that property businesses should pay particular attention to.
1. Recording Rental Payments Against the Wrong Tenant or Property
One of the most common accounting problems occurs when rental payments are entered against an incorrect tenant, lease, or property account. This can happen when several tenants pay similar amounts or when accountants manually process numerous transactions across different buildings.
For example, a property company managing residential apartments in Dubai may receive several rental installments on the same day. If a payment is assigned to the wrong tenant, one account may incorrectly show an outstanding balance while another appears fully paid. Such discrepancies can lead to unnecessary collection follow-ups and confusion during financial reconciliation.
A dedicated rental payment accounting system helps maintain clearer connections between tenant profiles, lease agreements, installment schedules, and recorded collections. When transactions are associated with the correct rental accounts, finance teams can review payment histories and investigate unmatched amounts more efficiently.
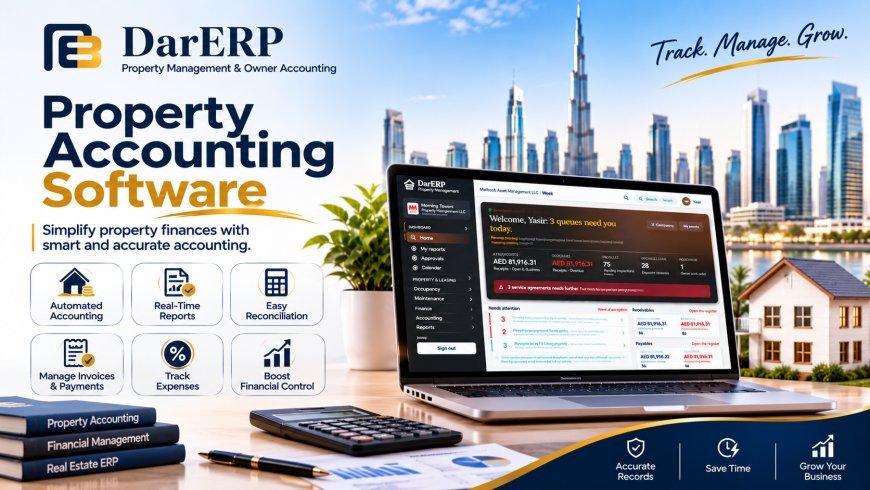
DarERP helps real estate businesses organize property and tenancy information alongside related financial activities, providing a more consistent foundation for rental bookkeeping.
Accurate payment allocation also supports clearer tenant statements and reduces the time spent correcting account balances.
2. Mixing Property Expenses and Miscalculating Profitability
Another costly mistake is recording expenses without associating them with the correct building, rental unit, or owner. Property management companies regularly pay for maintenance work, contractor services, cleaning, utilities, and other operating requirements. When these transactions are entered under general expense categories without proper property references, the financial performance of individual assets becomes difficult to evaluate.
Consider a business managing two commercial buildings. One property may require extensive air conditioning repairs, while the other has relatively low maintenance expenses. If both buildings' costs are combined without appropriate allocation, management may incorrectly assume that their operating performance is similar.
A structured property expense allocation system helps accountants classify costs according to the relevant asset and expense category. This makes financial reporting more meaningful and allows management to examine rental income alongside actual operating expenditure.
For businesses evaluating property profitability, accurate cost allocation is essential.
A building generating high rental revenue may still produce a weaker financial return if maintenance and operating expenses are not properly controlled. Reliable expense records help businesses recognize these differences before making investment or budgeting decisions.
3. Handling Security Deposits as Rental Income
Security deposit accounting is an area where incorrect financial classification can create significant reporting problems. When tenants provide deposits at the beginning of their rental agreements, those amounts are generally held against contractual obligations and may need to be refunded at the end of the tenancy.
Recording refundable deposits as ordinary rental income can overstate revenue and understate liabilities. This may also create difficulties when tenants move out and request the return of their deposits.
A reliable tenant security deposit accounting process helps maintain separate records for deposits received, amounts held, applicable deductions, and refunds processed.
For example, if a tenant pays a security deposit of AED 5,000, the accounting records should reflect the appropriate financial obligation rather than automatically treating the entire amount as earned rental revenue.
DarERP Property Management Software brings tenancy administration and financial information into a connected environment, helping businesses maintain the records needed to distinguish rental transactions from deposit-related obligations.
However, businesses must still apply the appropriate accounting policies and contractual requirements when classifying and settling deposits.
4. Making Errors in Owner Payments and Financial Statements
Property management companies frequently collect rental income and pay expenses on behalf of different landlords. Each owner may have separate properties, management fee arrangements, maintenance responsibilities, and payment instructions.
When accountants manually calculate owner balances using disconnected spreadsheets, incorrect deductions or payment allocations can affect financial statements and landlord distributions.
For example, a maintenance invoice belonging to one landlord's property might accidentally be deducted from another owner's rental income. Even when the amount is relatively small, such errors can damage confidence in the management company's financial procedures.
An integrated landlord accounting system helps maintain separate owner ledgers and associate rental collections, operating expenses, management charges, and distributions with the appropriate ownership records.
This makes it easier for accountants to review how an owner balance was calculated and identify supporting transactions.
Businesses using DarERP Property Management Software UAE can establish more consistent links between ownership records and property-related financial information, providing a clearer basis for reviewing landlord accounts.
Transparent owner statements are particularly important for companies managing rental assets on behalf of multiple investors.
5. Skipping Regular Reconciliation and Financial Reviews
A final accounting mistake is allowing financial records to remain unreconciled for extended periods. Rental collections, supplier payments, bank transfers, refunds, and accounting adjustments should be reviewed regularly to ensure recorded balances reflect actual financial activity.
When reconciliation is delayed, small discrepancies can accumulate and become more difficult to investigate. Accountants may struggle to identify when an incorrect entry occurred or which transaction caused a balance difference.
A specialized property accounting and reconciliation process helps maintain organized transaction references, payment histories, and financial records. Depending on the platform, bank statement imports or transaction-matching functions may further support these activities.
For example, if a recorded rental payment does not appear in the corresponding bank account, the discrepancy should be investigated before financial reports are finalized.
Regular reconciliation also helps identify duplicate entries, missing transactions, and incorrect payment allocations.
Accounting software can simplify financial verification, but it cannot replace consistent review procedures and professional financial judgment.
Key Features That Help Reduce Property Accounting Errors
Selecting the right accounting platform can help businesses address common financial risks while improving record organization.
Important capabilities include:
-
Rental and transaction controls: Tenant ledgers, installment tracking, payment references, post-dated cheque management, security deposit records, and accounts receivable monitoring.
-
Financial accuracy and oversight: Property expense allocation, owner accounting, reconciliation tools, transaction histories, approval permissions, and property-level financial reporting.
These functions work best when financial records are connected with accurate property and tenancy information. Businesses should also maintain clear accounting responsibilities and regularly verify transactions to prevent incorrect data from affecting reports.
How Property Accounting Software Improves Financial Accuracy
Property accounting software supports more dependable bookkeeping by maintaining a consistent relationship between financial transactions and the properties they concern. Accountants can review rental collections, identify outstanding balances, classify expenses, and maintain owner-related financial records through structured processes.
This reduces the need to repeatedly transfer information between spreadsheets and separate applications. It also makes discrepancies easier to investigate because transaction histories and supporting details can be maintained within the same accounting environment.
For larger real estate portfolios, these improvements can reduce administrative complexity and help finance departments work more efficiently.
The benefit is not simply faster data entry. It is having financial information that can be verified, explained, and used confidently for management decisions.
Additional Accounting Practices Real Estate Businesses Should Follow
Software adoption is only one part of maintaining accurate property finances. Businesses should also establish regular accounting reviews, appropriate approval procedures, and consistent record-keeping standards.
Finance teams should confirm that rental schedules match signed agreements, expenses are supported by valid documentation, and owner distributions have been properly authorized.
For UAE property businesses, applicable VAT treatment, financial record retention, and reporting obligations should also be considered. Different property transactions may have different accounting and tax implications.
Maintaining proper internal controls helps ensure that software supports responsible financial management rather than becoming another source of inaccurate records.
When Should a Business Upgrade Its Property Accounting System?
A business may need to reconsider its accounting tools when transaction errors become frequent, reconciliation takes excessive time, or financial reports cannot be prepared without manually combining several records.
Other warning signs include difficulty tracking outstanding rental balances, inconsistent expense allocation, delayed owner statements, and uncertainty about security deposit liabilities.
These challenges often become more noticeable as property portfolios expand.
Before implementing new software, businesses should review their existing financial information, correct inaccurate balances, and identify the accounting processes requiring improvement.
A careful transition helps prevent historical errors from being transferred into the new system.
How to Choose Software That Supports Better Accounting Control
When comparing property accounting solutions, businesses should evaluate the platform's ability to maintain tenant-specific transactions, property expense records, deposit liabilities, owner accounts, and reliable financial statements.
Security and user permissions are also important because accounting responsibilities should be assigned to appropriate employees.
A practical demonstration should include common scenarios such as allocating a rental payment, correcting an incorrect entry, recording a security deposit, processing a maintenance invoice, and reconciling an owner balance.
Testing these situations helps businesses determine whether the platform supports their actual accounting requirements.
Final Thoughts
Accounting mistakes can affect rental collections, property profitability, landlord relationships, and the reliability of financial reports. Incorrect payment allocations, mixed property expenses, poorly classified security deposits, inaccurate owner balances, and delayed reconciliation are among the problems real estate companies should actively prevent.
Property Accounting Software helps reduce these risks by organizing financial transactions, maintaining clearer account relationships, and supporting consistent bookkeeping procedures.
Although technology cannot eliminate every accounting error, it provides businesses with better tools for reviewing financial information and identifying discrepancies.
For UAE landlords, developers, and property management companies, combining specialized accounting software with effective financial controls can support greater accuracy, transparency, and confidence in everyday real estate accounting.
Frequently Asked Questions
1. What accounting mistakes can property accounting software help prevent?
Property accounting software can help reduce incorrect rental payment allocations, misclassified property expenses, security deposit errors, inaccurate landlord balances, and reconciliation problems. It supports structured transaction records and makes financial information easier to review.
2. Can property accounting software automatically eliminate accounting errors?
No. Property accounting software can reduce certain manual mistakes and improve transaction organization, but accurate results still depend on correct data entry, suitable accounting configurations, financial controls, and regular reconciliation.
3. Why is property accounting software important for UAE real estate businesses?
Property accounting software helps UAE real estate businesses organize rental collections, post-dated cheques, property expenses, tenant deposits, owner payments, and financial reporting. It provides a more structured accounting process for companies managing multiple rental properties and investors.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0