





What Are Debtors? Meaning, Types, Examples, and Importance
Understand what debtors are, their role in accounting, common types, practical examples, and effective ways to manage outstanding payments and cash flow.

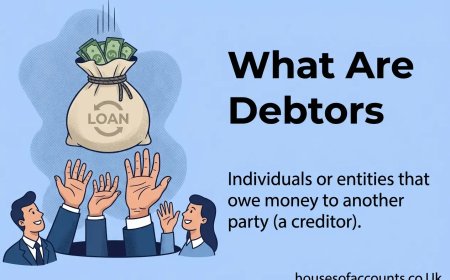
Understanding what are debtors is important for business owners, accounting students, and anyone who wants to understand how credit transactions affect financial records. Debtors are individuals, businesses, or organisations that owe money to another party. In business, they commonly arise when a company supplies goods or services and allows the customer to pay at a later date.
Debtors help businesses offer flexible payment arrangements, attract customers, and increase sales. However, money owed is not the same as money received. Until a customer pays an invoice, the business cannot use that amount to cover expenses such as salaries, rent, stock, or utility bills. Understanding what debtors are and how they are managed helps businesses maintain accurate accounts, control financial risks, and plan their cash flow more effectively.
What Are Debtors in Accounting?
In accounting, a debtor is a person or organisation that owes money to a business. The term most commonly refers to customers who purchase goods or services on credit.
For example, a supplier sells office furniture worth £3,000 to a company and allows 30 days for payment. The purchasing company owes £3,000 to the supplier and is therefore a debtor until the invoice is paid.
The amount owed is generally recorded as accounts receivable. This balance usually appears as an asset on the supplier's balance sheet because it represents money the business expects to collect. Whether a receivable is classified as a current or non-current asset depends on the expected collection period and the applicable accounting rules.
A debtor does not necessarily have an overdue account. A customer whose payment deadline has not yet arrived is still a debtor because the amount remains outstanding.
Types of Debtors
Businesses may deal with different types of debtors depending on how the debt originates.
1. Trade Debtors
Trade debtors are customers who owe money for goods or services supplied during normal business operations.
For example, a clothing wholesaler sells £5,000 worth of products to a retailer on credit. The retailer becomes a trade debtor until it pays the invoice.
Trade debtors are common in wholesale, manufacturing, retail, construction, and professional services. Their balances can significantly affect a company's working capital, particularly when customers receive extended payment terms.
2. Non-Trade Debtors
Non-trade debtors owe money for transactions outside the company's usual sales activities. Examples may include recoverable employee advances, loans to other businesses, or amounts due under separate agreements.
Suppose a company lends an employee £800, which must be repaid over four months. The outstanding amount may be recorded as a receivable rather than as a trade debtor.
The correct classification depends on the purpose of the transaction and the company's accounting policies.
3. Other Receivables
Other receivables include amounts due from sources such as interest, rent, insurance claims, or tax refunds. These balances are often reported separately from trade receivables.
Keeping different types of receivables separate helps management identify where money is expected to come from and determine which outstanding balances need attention.
How Do Debtors Work in Accounting?
Debtors usually arise when a business makes a credit sale or completes another transaction that creates a right to receive payment in the future.
Step 1: Record the Credit Sale
Suppose a business sells goods worth £1,500 on credit. Ignoring tax and inventory entries, the basic journal entry is:
-
Debit: Accounts Receivable £1,500
-
Credit: Sales Revenue £1,500
The debit records the customer's outstanding balance. The credit records the revenue, assuming the applicable revenue recognition requirements have been met.
Step 2: Monitor the Outstanding Amount
The business records the invoice date, due date, customer details, and amount owed. An accounts receivable ledger allows staff to track each customer's balance and identify unpaid invoices.
Accounting software can help automate payment reminders, match incoming payments to invoices, and generate reports showing which accounts are overdue.
Step 3: Record the Customer's Payment
When the customer pays the full £1,500, the business records:
-
Debit: Cash or Bank £1,500
-
Credit: Accounts Receivable £1,500
The bank balance increases, and the amount owed by the customer decreases to zero.
If a customer cannot pay, the business must assess whether the balance is recoverable and recognise any required allowance for expected credit losses or bad debt expense under the relevant accounting framework.
Difference Between Debtors and Creditors
Debtors and creditors describe opposite sides of a financial relationship. A debtor owes money, while a creditor is entitled to receive it.
| Feature | Debtors | Creditors |
|---|---|---|
| Meaning | Parties that owe money | Parties to whom money is owed |
| Accounting position | Generally an asset for the business expecting payment | Generally a liability for the business required to pay |
| Common account | Accounts receivable | Accounts payable |
| Example | Customer purchasing goods on credit | Supplier providing goods on credit |
| Cash flow effect | Expected cash inflow | Expected cash outflow |
For example, a restaurant buys ingredients worth £2,000 from a supplier and agrees to pay within 30 days. The restaurant records an amount payable, while the supplier records an amount receivable. The restaurant is the debtor, and the supplier is the creditor.
Why Are Debtors Important for Businesses?
Managing debtors helps businesses protect their finances and make informed operational decisions.
Maintaining Cash Flow
A business may record strong sales but struggle to pay its bills if customers delay payment. Monitoring debtor balances helps management estimate future receipts and plan payments for wages, rent, inventory, and other operating costs.
Supporting Business Growth
Credit arrangements can make products and services more accessible to customers. They may encourage repeat orders, help businesses compete, and strengthen commercial relationships.
However, offering credit without assessing risk can create problems. A company needs to balance sales opportunities against the possibility of delayed or missed payments.
Improving Financial Reporting
Accurate debtor records help businesses report their assets correctly and understand how much revenue remains unpaid. They also support budgeting, cash flow forecasting, and financial analysis.
Identifying Payment Risks
Regularly reviewing outstanding accounts can reveal customers who repeatedly pay late or owe unusually large amounts. Businesses can respond by adjusting credit limits, requesting deposits, or changing payment terms where appropriate.
Practical Ways to Manage Debtors
A clear debtor management process helps businesses collect payments consistently and reduce avoidable delays.
Set Clear Credit Terms
Explain payment deadlines, accepted payment methods, and applicable late-payment conditions before supplying goods or services. Written terms reduce misunderstandings and provide a reference if a dispute arises.
Issue Accurate Invoices Promptly
Invoices should include the customer's details, invoice number, description of the goods or services, amount due, payment instructions, and due date. Correct invoices sent on time reduce administrative delays.
Review Aged Receivables
An aged receivables report groups outstanding invoices according to how long they have remained unpaid. Categories may include amounts not yet due, 1 to 30 days overdue, 31 to 60 days overdue, and more than 60 days overdue.
This report helps staff prioritise collection efforts and identify accounts that may require additional attention.
Follow Up on Overdue Invoices
Send reminders before payment deadlines when appropriate. If an invoice becomes overdue, contact the customer to confirm receipt, identify any problems, and agree on a payment date.
Keep records of conversations, disputes, and repayment arrangements so the business can follow up accurately.
Check Customer Creditworthiness
Before offering significant credit, consider the customer's payment history, financial circumstances, references, and the size of the proposed transaction. Set credit limits that reflect the level of risk the business can reasonably accept.
Common Challenges and Considerations
Managing debtors can present several challenges that affect a company's financial stability.
Late payments: Customers may delay payment because of cash shortages, internal approval procedures, or invoice disputes. These delays can leave a business without enough cash for daily expenses.
Bad debts: Some customers may become unable or unwilling to pay. Businesses should assess the likelihood of collection and account for expected credit losses in accordance with applicable accounting standards.
Customer concentration: Relying heavily on a small number of customers can increase risk. If one major debtor fails to pay, the resulting cash shortage may be significant.
Recordkeeping errors: Duplicate invoices, incorrect balances, and payments allocated to the wrong accounts can make debtor records unreliable.
Businesses can reduce these risks through regular reconciliations, consistent documentation, clear credit policies, and timely communication.
Practical Benefits and Key Insights
Understanding what debtors are offers several useful insights for business management.
-
Better cash flow planning: Outstanding balances help businesses estimate when money may be collected.
-
More accurate financial records: Correct receivables information supports reliable reporting.
-
Reduced collection risk: Regular monitoring helps identify overdue accounts before they become difficult to recover.
-
Improved credit decisions: Customer payment histories help businesses establish suitable credit limits.
-
Clearer performance analysis: Comparing sales with actual collections helps management understand how efficiently the business converts credit sales into cash.
One important distinction is that revenue, profit, and cash are not the same thing. A credit sale may increase recognised revenue without immediately increasing the bank balance. Businesses should therefore monitor outstanding receivables alongside sales and profitability.
Frequently Asked Questions (FAQs)
1. What are debtors in simple words?
Debtors are people or organisations that owe money to another party. A customer who purchases goods on credit and agrees to pay later is a common example.
2. Are debtors assets or liabilities?
For the business expecting payment, debtors are generally assets because they represent money receivable. For the party that owes the money, the corresponding obligation is generally a liability.
3. What is an example of a debtor?
If a company provides consulting services worth £600 and gives the customer 30 days to pay, the customer is a debtor until the invoice is settled.
4. What is the difference between debtors and accounts receivable?
A debtor is the person or organisation that owes money. Accounts receivable is the accounting balance representing money owed to a business, commonly by customers who purchased goods or services on credit.
5. How can a business reduce overdue debtor balances?
A business can reduce overdue balances by setting clear payment terms, assessing customer creditworthiness, issuing accurate invoices promptly, reviewing aged receivables, and following up professionally when payments are late.
Conclusion
Understanding what debtors are is essential for learning accounting and managing business finances. Debtors are individuals or organisations that owe money, commonly because they have received goods or services on credit. These amounts are generally recorded as receivables and monitored until payment is collected or another accounting treatment becomes necessary.
Businesses can manage debtors more effectively by setting clear credit terms, maintaining accurate records, reviewing outstanding invoices, and communicating consistently with customers. These practices help reduce payment delays, identify financial risks, and improve cash flow planning. Effective debtor management allows businesses to protect their working capital, maintain reliable financial records, and support sustainable operations.
What's Your Reaction?
 Like
0
 Dislike
0
 Love
0
 Funny
0
 Angry
0
 Sad
0
 Wow
0